How Investors Should View Narrowing Market Breadth
In the past six weeks or so, we’ve seen a sharp narrowing of market breadth in the U.S., which means fewer individual stocks are participating in the market’s gains—even as major indexes continue trading near record highs. September was particularly narrow. Technology gained approximately 5.5%, while nine S&P 500 sectors finished the month in negative territory.
As breadth has narrowed, familiar fears have returned.
Some readers may recall 2024, when the “Magnificent Seven” were dominating returns and many worried the market was over-concentrated in a handful of tech behemoths. Today, fewer than half of S&P 500 stocks are trading above their 200-day moving averages, and more than 200 companies in the index have posted negative returns in 2026. As I write, the median stock is up only about 4%, compared with a roughly 14% gain for the overall S&P 500. 1
But the reckoning for over-concentration never really arrived in 2024, and I don’t think investors should read too much into the narrowing trend we’ve seen in recent weeks.
For one, the equal-weight S&P 500, which gives each company the same influence regardless of its market capitalization, has generated a total return of approximately 12.5% this year. That trails the return for the market-cap-weighted S&P 500 by a couple of percentage points, but it’s still a substantial gain. In my view, this speaks to the ability to diversify away some of the over-concentration risk.
There is also the fact that while price breadth has narrowed in the equity market over the past several weeks, earnings breadth is strong and broadening.
According to our colleagues at Zacks Investment Research, S&P 500 earnings are expected to grow 24.3% year-over-year in the third quarter, on 11.5% higher revenues. Removing the Technology sector reduces expected Q3 earnings growth from 24.3% to 14.2%, which is a meaningful step down but still points to quite strong overall earnings growth—particularly considering the higher borrowing costs and energy prices I’ve written about recently.2
All told, Zacks currently expects 15 of its 16 sectors to report positive year-over-year earnings growth in Q3, with six sectors projected to generate double-digit increases. Outside Technology, for instance, Industrial Products earnings are expected to rise 13.3%, Transportation 10.9%, and Basic Materials 29.7%.
The earnings outlook also continues to improve, which is noteworthy because analysts typically lower their estimates as a quarter progresses. Indeed, over the past decade, S&P 500 earnings estimates have declined by an average of 2.1% during the first two months of a quarter. But recently we’ve seen the opposite, with upward revisions continuing into Q4. According to Zacks Investment Research, positive Q4 revisions are showing up in seven sectors, including Aerospace, Construction, Industrials, Finance, and Transportation.
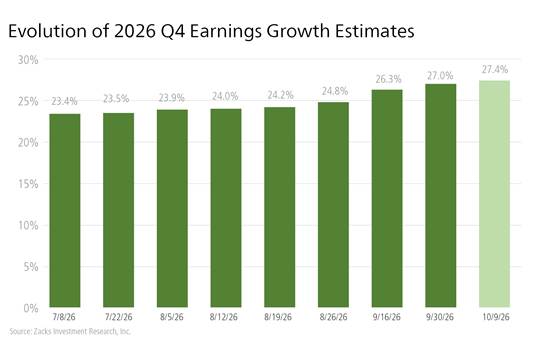
Remember that stock prices reflect expectations for the future, and investors can become more or less enthusiastic about particular companies and sectors very quickly. For instance, we saw capital rotate into small-caps earlier this year, followed by a renewed preference for mega-cap Technology as investors reassessed interest rates, energy costs, and AI opportunities.
But earnings trends tend to evolve more gradually, and at least for now, they continue to show that companies outside the market’s largest Technology names are growing profits. This again argues for a broadly diversified approach.
Q3 earnings season is getting underway this week, meaning we’ll soon have a much clearer picture of whether analysts’ expectations are being met. I’ll be paying particular attention to results and management commentary outside Technology, where the gap between stock-price performance and expected earnings growth is especially interesting.
Bottom Line for Investors
Narrow market leadership is worth watching, particularly when some of the largest companies account for an outsized share of index returns. But I think investors should distinguish between weakness in stock prices and weakness in corporate fundamentals. The two can move in different directions for extended periods, as we’ve seen throughout this year.
For now, the earnings outlook gives me reason to remain constructive. Even excluding Technology, our analysts are projecting double-digit earnings growth across other sectors in the S&P 500. That suggests a broader foundation of corporate profitability than recent price action might imply.
Disclosure
2 Zacks Investment Research. October 9, 2026. “Estimates Keep Rising as Q3 Earnings Season Takes Center Stage.”
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.
The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security's U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.