Why This Rate Hike Probably Won’t Be the Last
When Federal Reserve Chairman Kevin Warsh was appointed, much of the market concern centered around whether he would push too hard for monetary easing—at a time when inflation was above target and the economy was growing steadily.
What a difference a few months of hot inflation can make.
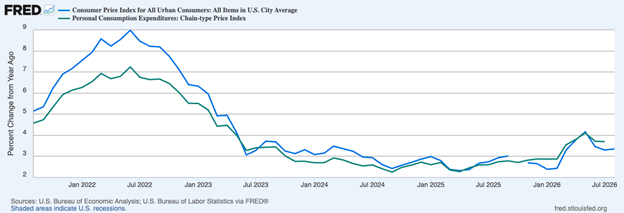
August CPI showed prices rising 0.4% month-over-month and 3.4% year-over-year, and the Fed’s own September projections now put 2026 PCE inflation at 3.7% and core PCE inflation at 3.4%, both well above its 2% target.1
CPI (blue line) and the PCE Price Index (Green Line) Have Been Pressured Higher in 2026
What Hotter Inflation and Shifting Fed Policy Could Mean for Your Portfolio
Inflation continues to run hotter than expected, raising questions about how the Federal Reserve may respond and what higher interest rates could mean for investors.
Our latest September Stock Market Outlook Report³ examines how persistent inflation and changing expectations for Fed policy could affect the markets and your portfolio.
Inside, you’ll learn:
- Asset allocation guidelines for today’s market environment
- Expert forecasts for inflation, rates, and economic trends
- Industry tables and rankings to help you spot opportunities
- Buy-side and sell-side consensus insights at a glance
- And much more!
Claim your complimentary copy of the report to learn how persistent inflation and shifting Fed policy could affect your portfolio in the months ahead.
IT’S FREE. Download our September Stock Market Outlook Report3
I want to be fair in making the point that the numbers do not suggest inflation is spiraling out of control, especially given the outsized impact of higher energy prices. But we’re certainly seeing an end to the downward trajectory that started in the summer of 2022, with recent price pressures being enough to motivate all 12 of the Fed’s voting members to push rates higher.
History tells us we should expect more hikes from here.
Federal Reserve rate changes tend to be serially correlated, meaning policy moves often come in sequences rather than isolated steps. Looking at actual changes in the federal funds target since 2003, there have been 60 rate changes. On the 59 occasions when one change was eventually followed by another, 52 of them—or roughly 88%—moved in the same direction as the prior change.4 In other words, a hike is almost always followed by another hike, with the same going for cuts.
The individual cycles make the pattern easier to see. The Fed raised rates 17 consecutive times from 2004 through 2006. It then delivered 11 hikes across 2022 and 2023. More recently, the Fed cut rates six consecutive times across 2024 and 2025 before reversing direction last week. This serial correlation is sometimes referred to as “interest-rate smoothing,” with central banks generally preferring to adjust policy incrementally as they receive new information about inflation and growth—rather than making one large move and immediately reversing course.
The Fed’s own projections point in the same direction today. Following this week’s increase, the median policymaker projection puts the federal funds rate at 4.1% at year-end, compared with the current midpoint of 3.875%. 16 of 18 policymakers expect at least one additional increase before year-end.
For investors, the big picture shows us a world where financial conditions are gradually being tightened. The European Central Bank and Bank of Japan have recently raised rates, while the Bank of England has adopted a more hawkish posture as energy prices and inflation remain elevated. It looks to me like a renewed global tightening cycle, which I think could have implications for equity market volatility (as I wrote about recently).
It’s a trend worth watching closely, though I expect this tightening cycle to be far less aggressive than what investors experienced in 2022 and 2023. In other words, not enough to derail the bull market. The larger questions remain whether inflation continues to moderate, whether economic and earnings growth hold up, and whether tighter policy eventually begins to materially weaken demand. When I zoom out and take it all into consideration, I don’t think two or three quarter-point hikes are meaningful enough to materially change the earnings or economic backdrop on their own.
Bottom Line for Investors
This week’s quarter-point rate hike was widely expected, and I do not think investors should overhaul portfolios because the federal funds rate moved 25 basis points higher. The more interesting signal is the direction of policy. Fed rate changes have historically tended to come in sequences, the central bank’s own projections point to additional tightening, and other major central banks are confronting many of the same inflation pressures. It’s something to watch, but probably not enough to fundamentally alter the investment landscape, in my view.
The final takeaway that I think deserves attention is the idea that pressure could/would compromise Federal Reserve independence. In my view, the rate hike decision provides a useful piece of evidence in the other direction. With midterm elections approaching and the administration openly favoring lower borrowing costs, the Fed still voted unanimously to raise rates in response to inflation. That looks like a central bank responding to economic data, not political pressure. This point becomes even more salient if the Fed decides to raise rates again from here, which I believe will be the case.
As inflation and monetary policy continue to shape the investment landscape, staying focused on the data will be essential. Download our latest September Stock Market Outlook Report5 for a closer look at the forces driving today’s market—and what they could mean for your portfolio.
Inside, you’ll learn:
- Asset allocation guidelines for today’s market environment
- Expert forecasts for inflation, rates, and economic trends
- Industry tables and rankings to help you spot opportunities
- Buy-side and sell-side consensus insights at a glance
- And much more!
If you have $500,000 or more to invest, claim your complimentary copy of the report and see how shifting market trends could influence opportunities in the months ahead.
IT’S FREE. Download our September Stock Market Outlook Report5
Disclosure
2 FRED Fred Economic Data. September 11, 2026. Consumer Price Index for All Urban Consumers: All Items in U.S. City Average
3 Zacks Investment Management reserves the right to amend the terms or rescind the free Stock Market Outlook Report offer at any time and for any reason at its discretion.
4 Federal Reserve. September 16, 2026. Board of Governors of the Federal Reserve System.
5 Zacks Investment Management reserves the right to amend the terms or rescind the free Stock Market Outlook Report offer at any time and for any reason at its discretion.
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.
The Russell 2000 Index is a well-known, unmanaged index of the prices of 2000 small-cap company common stocks, selected by Russell. The Russell 2000 Index assumes reinvestment of dividends but does not reflect advisory fees. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.
The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security's U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.